
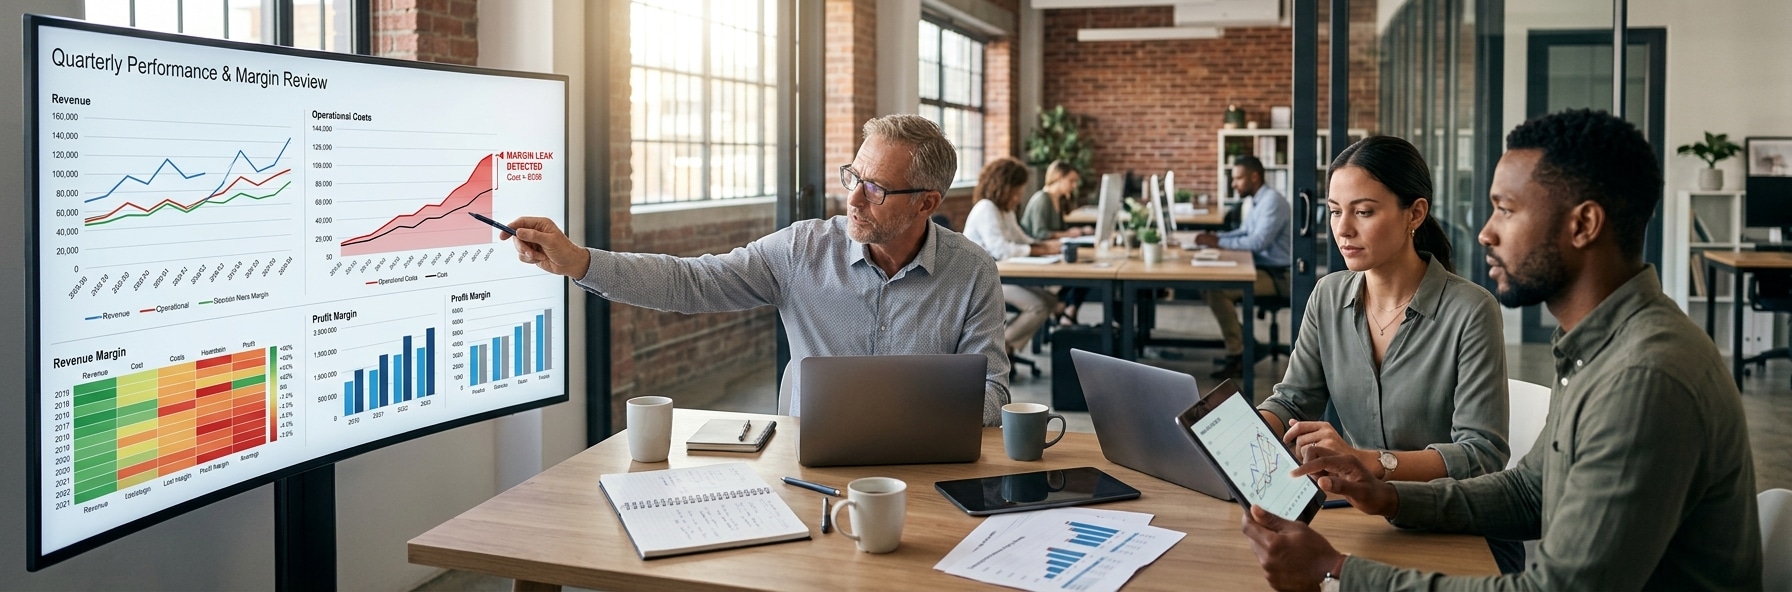
Margin leaks rarely announce themselves. Revenue grows, the pipeline looks healthy, and gross margin drifts down a point or two per quarter without any single decision causing it. By the time the trend is visible in annual results, it has usually been running for four to six quarters.
The reason is structural. A consolidated margin percentage is an average across every customer, product, and project, so it can hold steady while the distribution underneath it deteriorates badly. The leaks only become visible at the transaction level, measured the same way period after period.
Where the leaks hide
Five patterns account for most of the erosion in mid-market companies:
- Discount drift. Concessions granted to win a deal persist into renewals long after the competitive pressure that justified them
- Unbilled scope. Work delivered outside the original agreement goes uninvoiced because nobody owns the change order conversation
- Mix shift. Growth in a lower-margin line lowers blended margin even when every individual margin is stable, and it is routinely misdiagnosed as a cost increase
- Cost to serve. Freight, expedites, returns, and support hours vary widely by customer and usually sit in overhead rather than allocated where they belong
- Unrealized price increases. Announced increases fail to reach a share of invoices because of contract terms, system defaults, or oversight
What the analysis depends on
Transaction-level margin analysis is only as trustworthy as the data feeding it, which makes this a governance question before it is a reporting one. Before the numbers mean anything, you need agreement on who owns each definition and where it is calculated.
- A consistent customer and product hierarchy that does not change between periods
- Documented ownership of each metric, with one named owner rather than shared accountability
- Controlled access and change management on the systems producing the source data
- A month-end close that lands on a predictable schedule, so variances reflect the business rather than timing
Companies that skip this step produce analytics that swing for reasons unrelated to performance, and leadership quietly stops trusting the output. Settling definitions and decision rights first is what IT governance contributes to an analytics program.
Turning findings into recovered margin
Analysis that ends in a report changes nothing. The pattern that works is narrow: quantify each leak in dollars, assign one owner, set a date, and re-measure the same metric next quarter using an identical definition. Re-measurement is the step most often skipped, and the only one that proves the fix held. Sequence by dollars rather than by ease of execution.
How Windes helps
Finding a margin leak is an accounting and data problem before it is an analytics problem. Windes Advisory Analytics brings both to the same engagement:
- Transaction-level margin decomposition by customer, product, and channel
- Price realization and discount drift measurement against list and contract terms
- Cost-to-serve allocation that exposes unprofitable accounts hidden inside healthy averages
- A recurring measurement cadence with definitions that stay consistent period over period
As a CPA firm, we work from the underlying records rather than from a dashboard export, and Business Insights and FP&A can keep the resulting metrics in front of leadership once the analysis is built.
Do you know which customers lost margin last quarter? Talk to the Windes Advisory Analytics team.